
You have agreed on a veterinary practice purchase, but the lender's model changes the conversation. The debt payment, guaranty fee, equipment requirements, and cash remaining after closing can turn a seemingly affordable acquisition into a fragile one. A buyer may own the clinic on closing day and still lack enough liquidity for payroll pressure, a staffing gap, repairs, or slower collections.
The purchase price is only the starting point. Finance to buy a business means structuring debt around the practice's first year, not chasing the lowest rate or largest approval. In 2026, assess guaranty fees, amortization drag, transition costs, and post-close liquidity together. The right loan preserves operating room; the wrong one consumes it before ownership settles.
Why Financing Structure Determines Deal Viability
A clinic can show dependable revenue, a respected local reputation, and enough apparent cash flow to support a purchase. The financing structure still determines whether ownership begins with operating room or immediate pressure. One buyer recently faced a proposal with payments so high that, after the down payment, closing costs, and required operating funds, the clinic would have had too little liquidity for a staffing disruption or unexpected equipment repair.
The purchase price is only the first number
Start with the full cash requirement, not the seller's asking price. Payroll, inventory, transition support, software changes, repairs, professional fees, and equipment upgrades can arrive immediately after closing. A lender may approve the acquisition, yet the clinic can still lack enough cash to absorb ordinary disruption.
Amortization creates another hidden cost. A longer repayment period generally lowers the required monthly payment. A shorter period can reduce the time debt remains outstanding, but it consumes more operating cash each month. Choose the schedule against normalized cash flow and your staffing and growth plans, rather than selecting the shortest payoff period automatically.
Guaranty fees also belong in the purchase model. They increase the amount borrowed or the cash required at closing, depending on how the transaction is structured. Combine that cost with amortization drag, transition expenses, and the liquidity you want left in the operating account.
Market scale matters when you assess lender capacity and program availability. SBA data for FY2025 show 78,078 7(a) loans totaling $37.3 billion, while 7(a) and 504 lending combined reached $45.1 billion, as reported in SBA acquisition lender and program data. A separate analysis reports that roughly 10 million U.S. businesses are expected to change hands over the next decade in its acquisition-finance market coverage.
Practical rule: Ask two questions before accepting terms: “Can I close this purchase?” and “What cash will the practice have left after I close it?”
Debt affects your personal risk
Acquisition lenders examine your personal financial position, credit history, experience, and ability to support the business. The structure can therefore affect your personal exposure as well as the clinic's balance sheet. Excessive debt also limits your ability to respond to staffing, collections, and equipment problems with sound operating decisions.
Before signing a letter of intent, compare the proposed payment with a conservative version of practice cash flow. Remove questionable seller add-backs, account for normalized owner compensation, and test lower revenue alongside higher expenses. If the deal works only when every assumption holds, revise the structure before you proceed.
Review current borrowing conditions with a lender familiar with veterinary practices, including veterinary practice loan rates that may apply to your situation. The goal is a payment the clinic can carry while retaining enough liquidity to perform through the transition.
Comparing the Main Acquisition Loan Options
A veterinary acquisition can look affordable on paper and still leave the buyer short of cash after closing. The loan type determines more than the interest rate. It sets the amortization burden, guaranty fees, equity requirement, collateral expectations, and the liquidity available for payroll, inventory, repairs, and the first months of ownership.
SBA 7(a) financing can combine the practice purchase, goodwill, working capital, and selected acquisition costs in one package. A conventional loan may fit a buyer with substantial liquidity, strong credit, collateral, and a predictable operating record. Seller financing can close a valuation or equity gap, while equipment financing can keep specialized assets from inflating the main acquisition balance.
In 2026, independent market commentary places SBA 7(a) acquisition pricing around prime plus 2.5% to 2.75%, with approximately 10-year amortization. Loans above $350,000 carry a 2.77% guaranty fee in FY2026, according to current SBA acquisition-financing coverage. Include that fee in the transaction model. If it is financed, it also increases the balance that accrues interest and requires repayment.
| Loan Type | Typical Terms | Best For | Key Trade-Off |
|---|---|---|---|
| SBA 7(a) acquisition loan | Pricing around prime plus 2.5% to 2.75%, with about 10-year amortization; FY2026 guaranty fee applies above $350,000 | First-time buyers, goodwill-heavy practices, partner buy-ins, and acquisitions needing flexible uses of funds | Longer amortization can help cash flow, but the guaranty fee increases total borrowing cost |
| Conventional bank acquisition loan | Terms vary by lender, collateral, cash flow, and borrower strength | Buyers with strong financial resources and a practice with predictable earnings | May require more equity, stronger collateral, or tighter repayment expectations |
| Seller financing | Negotiated principal, rate, payment, and subordination terms | Filling a funding gap or aligning the seller with a smooth transition | Seller notes can compete with senior debt for monthly cash flow |
| Equipment financing | Repayment tied to specific imaging, surgical, laboratory, or technology assets | Buyers replacing or adding equipment during the acquisition | Asset-specific funding doesn't solve broader working-capital needs |
| Working capital line | Revolving access for operating expenses, subject to approval and availability | Payroll, pharmaceutical inventory, repairs, and uneven monthly cash flow | Available credit isn't the same as permanent liquidity, and usage creates additional debt |
SBA 7(a) is usually the starting point
SBA 7(a) financing is widely used for ownership transfers because it can support the purchase of an existing business and related acquisition needs. FY2025 data identify approximately $8.29 billion across roughly 7,003 change-of-ownership deals, with an implied average acquisition loan near $1.18 million. The same analysis reports a broader SBA 7(a) average loan size of $477,642, making acquisition transactions materially larger than the program-wide average. See the SBA financing statistics for acquisition lending for the underlying benchmarks.
Those larger balances make the payment schedule and post-close reserve especially important. SBA financing can preserve more buyer equity than a conventional structure when goodwill forms a large part of the purchase or available collateral is limited. The guaranty fee and long amortization still need to be modeled together. A longer schedule lowers the required monthly payment, while extending the period over which interest and principal affect the practice.
Conventional debt can be cleaner, but not automatically cheaper
A conventional loan can work well when the buyer has substantial liquidity, strong credit, meaningful collateral, and a practice with straightforward financial performance. The lender may offer a structure designed for the borrower and clinic rather than to a government-backed program's requirements.
Review the complete proposal. Compare the payment schedule, required equity, fees, covenants, collateral expectations, prepayment terms, and cash remaining after closing. A lower quoted rate may create more amortization drag if the repayment period is shorter. Use the main types of loans for veterinary practices as a starting framework, then test the actual proposal against conservative clinic cash flow.
Seller notes and equipment debt have specific jobs
A seller note belongs in the capital stack only when its terms support the practice after closing. It may bridge a valuation difference, align the seller with an orderly transition, or reduce senior debt. Review its payment, interest rate, maturity, subordination, and any required payments during the transition. A seller note used to make an unaffordable purchase appear financeable creates a second monthly obligation without improving operating capacity.
Equipment financing should match a defined asset need. Imaging, surgical, laboratory, and information technology equipment may warrant separate funding, keeping the acquisition loan focused on the practice purchase. Set repayment against the asset's expected useful life and the revenue it supports.
A working capital line handles uneven operating needs, such as payroll, pharmaceutical inventory, repairs, and seasonal collections. It does not replace cash reserved at closing. If the clinic needs repeated draws for ordinary payroll immediately after the purchase, the original capital structure left too little liquidity. Choose the loan mix that lets the practice absorb normal surprises while the new owner learns the business.
Documentation and Underwriting for Veterinary Practices
Lenders don't underwrite a veterinary practice from the purchase price alone. They need to see how the clinic earns money, how reliably clients pay, what the owner currently takes out of the business, and what changes after the transfer. A clean package helps the lender distinguish durable cash flow from temporary or personal expenses.
Start with the financial record
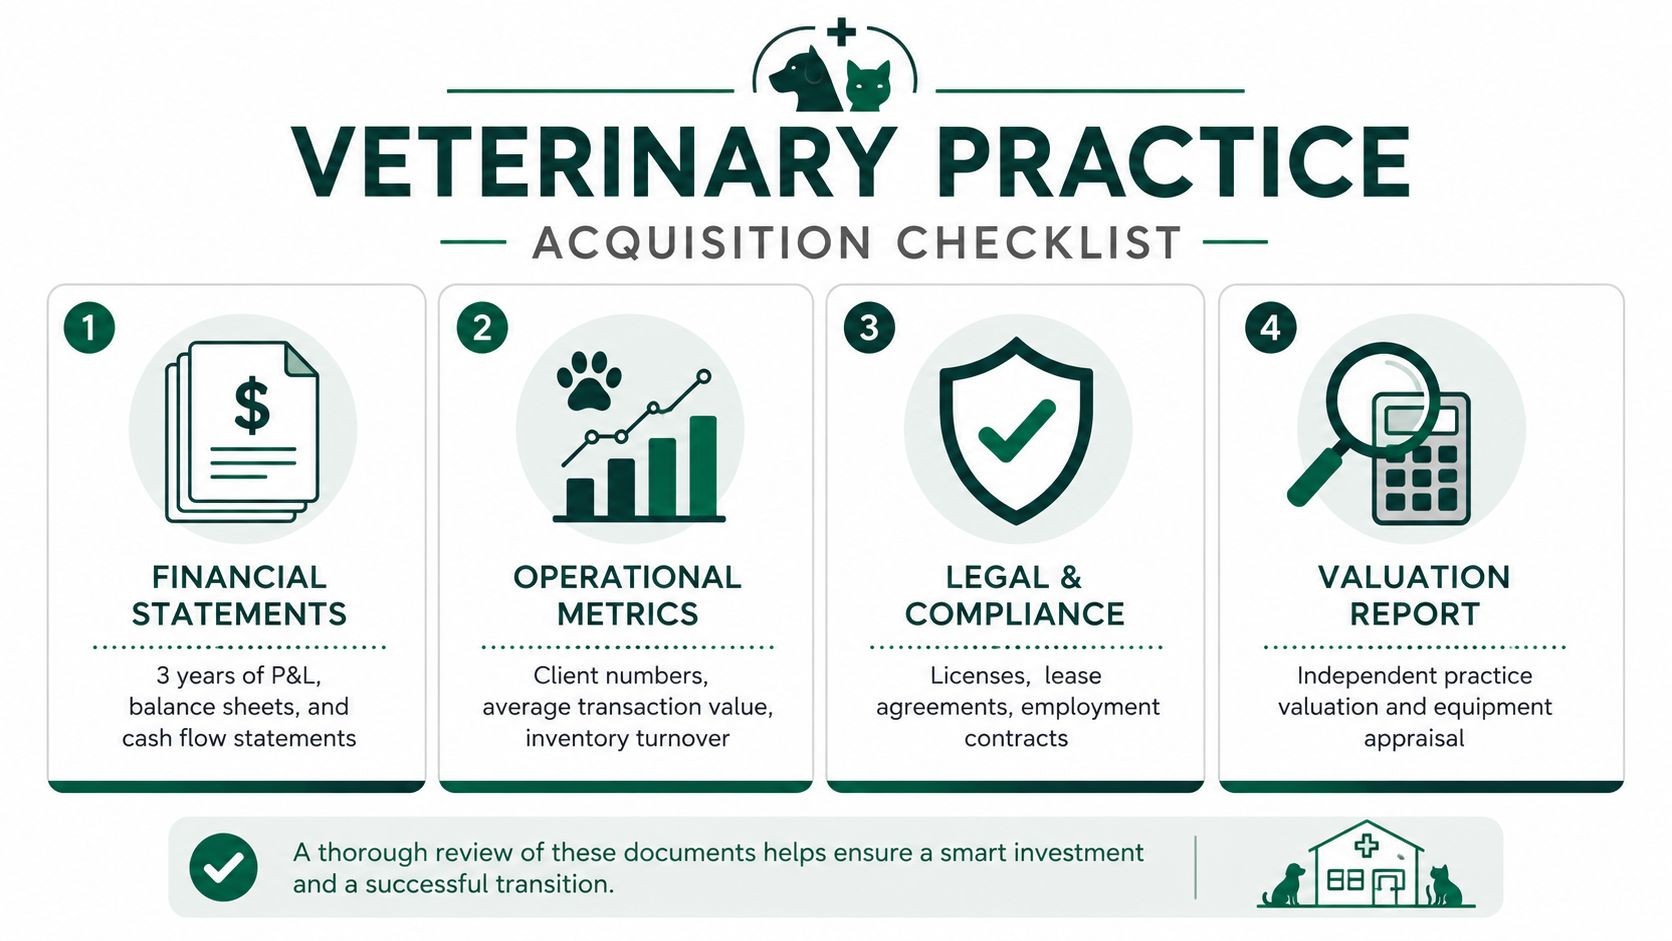
Prepare the core financial information before requesting a formal term sheet. That normally includes:
- Historical statements: Organize income statements, balance sheets, cash-flow information, and business tax returns for the available reporting periods.
- Current performance: Provide recent profit-and-loss information, balance-sheet data, debt schedules, and bank activity that reconcile with the accounting records.
- Seller adjustments: List every proposed add-back with supporting documentation. Personal expenses, one-time costs, and discretionary items need evidence, not broad labels.
- Buyer finances: Assemble personal tax returns, a personal financial statement, credit information, and a clear explanation of available equity.
- Transaction documents: Include the letter of intent, purchase-price allocation, proposed seller note, lease terms, and details about included equipment and real estate.
A lender will test whether seller-adjusted cash flow survives normalization. If the seller pays themselves unusually little, unusually much, or performs clinical and administrative work that you won't replicate, the lender must adjust the earnings picture. The number that matters is the cash flow available after paying a realistic replacement cost for the work required to operate the clinic.
Then explain the clinic operationally
Veterinary underwriting also benefits from operating detail. Show client counts, average transaction patterns, revenue by service line, appointment volume, inventory practices, staffing levels, and compensation arrangements. Client deposits and bank deposits should make sense alongside reported revenue.
Equipment deserves its own schedule. Identify age, ownership, outstanding liens, maintenance condition, depreciation, and replacement needs. A practice can show healthy historical earnings while carrying an aging dental unit, imaging system, or surgical platform that needs prompt investment.
Follow the underwriting sequence
The process is easier when you treat it as a sequence rather than a document scramble.
- Pre-qualification: Discuss the purchase concept, your experience, available equity, personal finances, and the practice's broad performance.
- Preliminary structure: Review the likely senior debt, seller financing, equipment needs, working capital, and expected cash remaining after closing.
- Full submission: Deliver the complete financial, operational, legal, and transaction package.
- Verification: Respond to questions about add-backs, revenue concentration, leases, staffing, tax filings, equipment, and valuation.
- Final approval: Satisfy conditions, finalize insurance and legal documents, confirm the use of funds, and coordinate the closing.
Organized processes can produce funding decisions as fast as 24 hours when documentation and lender criteria are met, based on the publisher's stated process capabilities. That speed depends on fit and completeness. It doesn't eliminate the need for diligence.
A missing tax return slows a file. An unsupported add-back weakens cash flow. A missing equipment appraisal creates a valuation problem.
Use the assets required for a veterinary practice loan to prepare collateral and equipment information early. Don't wait for underwriting to discover that the lease, licenses, contracts, or asset records are incomplete.
Structuring the Deal to Survive the First Year
The first 12 to 18 months after buying a practice expose weak assumptions quickly. Staff may leave, production may soften, equipment may fail, and your management workload may exceed the original plan. Size the loan around verified, stabilized earnings. Hold enough cash to operate through the transition before those earnings are fully under your control.
One independent analysis of FY2020 to FY2025 loan-level data reported 0.71% defaults for business acquisitions, compared with 1.99% for new-business loans and 1.43% for startups. The analysis is summarized in SBA loan default rates by loan use. An acquired practice gives you an existing earnings base, provided you verify the cash flow and protect it after closing. The default figures do not remove the need for disciplined underwriting.
Build the capital stack around resilience
Separate the money required to close from the cash required to operate. The structure may combine senior acquisition debt, buyer equity, a subordinated seller note, equipment financing, and a working capital facility. Uses can include purchase consideration, guaranty fees, other closing costs, equipment, transition expenses, and liquidity reserves.
Amortization creates another hidden cost. A payment that looks manageable on a stabilized forecast can restrict hiring, repairs, and owner compensation during the first year. Model the payment against realistic post-close cash flow, then calculate how much liquidity remains after the down payment, fees, and planned transition spending.
Stress-test the structure against practical disruptions:
- Revenue softness: Reduce projected revenue and check whether debt service remains manageable.
- Staff turnover: Include recruiting, temporary coverage, and higher compensation if key clinical employees leave.
- Equipment failure: Identify assets that could interrupt production and determine how repair or replacement would be funded.
- Inventory pressure: Reserve cash for pharmaceutical and medical supply purchases instead of relying on expensive short-term debt.
- Owner capacity: Confirm that one veterinarian will not carry clinical care, management, finance, recruiting, and integration indefinitely.
A partnership can change the risk profile. A cohort analysis of SBA acquisition loans approved from FY2010 through FY2017 found 6.8% default for solo buyers versus 3.8% for partnerships. For acquisitions under $150,000, the comparison was 7.6% versus 4.5%, while deals of $1 million or more showed 2.8% versus 2.1%. The findings appear in research on reducing buyer failure before close.
Use a co-buyer or operating partner only when the practice needs complementary clinical, operational, or financial capacity. Document roles, authority, equity, distributions, and accountability before closing. A partner added only to make the structure appear safer creates another source of risk.
Treat repeat acquisitions differently
A second location should have its own cash-flow case. Separate the locations' revenue and expenses, identify which clinic carries each obligation, and measure whether shared administration reduces costs or adds complexity.
Recent 2026 market coverage reports that the SBA doubled the combined 7(a) and 504 borrowing limit to $10 million, expanding capacity for repeat buyers. That change is discussed in a 2026 guide to SBA acquisition financing. Higher borrowing capacity does not make the payment affordable. Protect the established clinic, preserve post-close liquidity, and stage expansion only after the newer location demonstrates dependable cash flow. Fast initial answers are helpful, but the path through final underwriting determines whether the deal sustains beyond year one.
Choosing the Right Financing Structure for Your Situation
The right structure depends on what can go wrong after closing. Start with cash-flow resilience, then compare rates. A lower rate with a shorter amortization may cost less over the life of the loan while creating a payment that restricts hiring, repairs, and growth at exactly the wrong time.
First-time buyer acquiring one established practice
For a first-time owner buying a stable clinic, an SBA 7(a) structure may provide useful flexibility when the transaction includes goodwill, working capital, and equipment. The key test is whether the normalized cash flow supports the payment after paying you a realistic compensation level.
Don't use the smallest possible down payment as the primary objective. Retaining cash can be valuable, but excessive debt leaves less room for transition mistakes. Compare two models, one with more equity and lower debt, and one with more retained liquidity and higher payments. Then test each against lower revenue and an unexpected staffing expense.
Veterinarian buying a partner's share
A partner buy-in is often operationally simpler because you already understand the clinic's systems, clients, staff, and culture. That familiarity doesn't replace valuation discipline. Confirm the price, ownership rights, distributions, management duties, debt obligations, and treatment of future capital contributions.
The seller note can be useful here, particularly if the departing partner wants continuing economic alignment during the transition. Negotiate payment terms that don't drain the practice. A standby or subordinated note may preserve senior lender requirements and reduce immediate cash pressure, but the legal documents must clearly define when payments begin and what conditions apply.
Multi-location group planning phased growth
A growing group should separate acquisition financing from expansion financing whenever possible. Buying a clinic, renovating it, adding staff, and launching another site can create several simultaneous cash demands. If one loan carries all of them, the group may lose visibility into which investment is producing returns.
Create a location-level forecast. Assign revenue, payroll, rent, supplies, debt service, and capital spending to each site. Shared costs should have a clear allocation method. This helps you identify whether the first clinic can safely support the second or whether the second must reach a defined performance threshold before further expansion.
Buyer adding equipment during the purchase
If the acquisition requires major imaging or surgical equipment, don't bury every asset inside the goodwill purchase loan without comparing alternatives. Equipment financing may align the repayment with the asset's useful life and keep the main acquisition debt focused on the ownership transfer.
The best proposal isn't necessarily the one with the lowest nominal interest rate. It's the one that leaves the clinic with enough cash to operate, gives you a manageable payment under stress, and matches each debt instrument to the asset or need it funds.
Your Next Steps to Close the Deal
Start before you sign a purchase agreement. Build a personal financial picture, review the target clinic's statements and deposits, identify equipment and lease issues, and estimate the cash required after closing. If you wait until the agreement is signed to discover that the practice needs new equipment or carries weak documentation, you'll negotiate under pressure.
Use this sequence:
- Define your capacity: Establish the equity you can invest without exhausting personal and business liquidity.
- Normalize the practice: Recast seller cash flow, owner compensation, one-time expenses, staffing costs, and equipment needs.
- Choose the lender category: Compare SBA-focused, conventional, equipment, seller-financed, and working-capital structures based on the transaction.
- Prepare the file: Assemble financial statements, tax returns, debt schedules, leases, contracts, licenses, valuation materials, and a clear transition plan.
- Model the post-close year: Include debt service, payroll, inventory, repairs, taxes, professional fees, and planned capital spending.
- Compare proposals completely: Review guaranty fees, amortization, equity requirements, collateral, covenants, prepayment terms, seller-note restrictions, and remaining liquidity.
A veterinary-focused lender should understand how appointment volume, client deposits, pharmacy inventory, staffing, and clinical production affect repayment. Ask who will review the file, what information they need, how they treat add-backs, and what conditions could delay closing. A fast initial answer is useful, but a clear path through final underwriting matters more.
If you're evaluating a purchase now, don't wait for the final valuation report to begin financing conversations. Prepare the financial package, identify your preferred structure, and test the debt against a difficult first year before you make an offer.
Veterinary Practice Loans offers financing for veterinary practice acquisitions, partner buy-ins, equipment purchases, working capital, and expansion, with underwriting focused on clinic revenue, deposits, and cash flow. Visit Veterinary Practice Loans to discuss your acquisition structure, compare the true cost of available debt, and protect the liquidity your practice will need after closing.
